
StocksEquities, earnings & valuations
WhiteHorse Finance's manager seeks to move the BDC's loans into a $680M continuation vehicle and delist it, PitchBook says
H.I.G.'s WhiteHorse Capital is seeking to move all of WhiteHorse Finance's assets into a roughly $680M continuation vehicle run by the same manager and to delist the BDC, PitchBook reports. The company has confirmed only a strategic review. Its shares trade about one-third below NAV.
From the Clark Street Value article of November 19, 2026 and cited sources: According to PitchBook, the vehicle would combine WHF's loans with assets from its joint venture with Ohio's State Teachers Retirement System. [2] [4] [5]
SOURCES[2] PitchBook: WhiteHorse Finance BDC pursues $680M… pitchbook.com[4] SEC 8-K: Strategic review (15 Sep 2026) sec.gov[5] Investing.com: Special committee formed investing.com
 AT Pulse research deskPublished · Updated · 5 min read · AI-assisted analysis
AI-assisted, not human-edited. Methodology Corrections Who owns this site
- What happened
- According to PitchBook, the vehicle would combine WHF's loans with assets from its joint venture with Ohio's State Teachers Retirement System. [2] [4] [5]
- Original source
- Clark Street Value article, independent perspective
- Brief by
- AT Pulse research desk AI-assisted; publisher and contact on the desk page
- When
- November 19, 2026 article published
- Covered
- Nov 20 edition
- Evidence
- 12 sources across 11 sites
- 1WhiteHorse Finance: BDC Pursuing Strategic Alts…clarkstreetvalue.blogspot.com
- 2PitchBook: WhiteHorse Finance BDC pursues $680M…pitchbook.com
- 3Finviz: WHF Q3 2025 release, dividend resetfinviz.com
- 4SEC 8-K: Strategic review (15 Sep 2026)sec.gov
- 5Investing.com: Special committee formedinvesting.com
- 6Yahoo Finance syndication of PitchBookfinance.yahoo.com
Reach: not measured yet
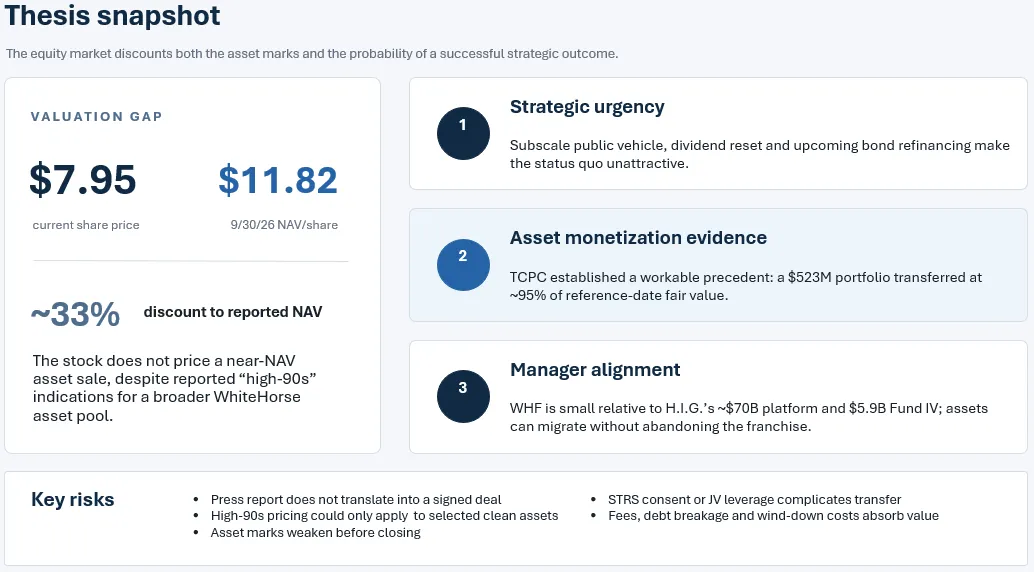
According to PitchBook, the vehicle would combine WHF's loans with assets from its joint venture with Ohio's State Teachers Retirement System. Private-credit secondaries investors would fund it. Bids were reported in the high 90s (cents on the dollar), and Jefferies is advising. A September 8-K confirms that a special committee of independent directors is weighing a sale or other transaction. The filing sets no deadline and does not commit to any outcome. [2] [4] [5]
The reported bid range matters because of the discount. Q3 NAV was $11.82 per share, while the stock traded near $7.95. A blogger who owns WHF shares puts the value of the reported structure at about $10.50 per share. That figure is his own estimate, not a disclosed deal price. [1] [7]
WHF's earnings are under strain. Core NII was $0.224 per share in Q3, below the $0.25 dividend, which had already been cut from $0.385 in November 2025. Notes also mature in December. The 2021 offering was $75M, but management cited $85M on the earnings call. [3] [7] [8] [9]
The closest precedent is BlackRock TCP Capital. In August it sold 95% of a vehicle holding about $523M of loans to Pantheon and expected NAV to fall about 10.4%. TCPC sold part of its book and kept operating. The reported WHF deal would move everything and delist the company, with the manager on both sides of the transaction. [11] [12] [1]
What is confirmed: a special-committee review, a dividend that core earnings do not cover, and notes maturing in December.
Read the full assessment
What follows from that: a high-90s bid could narrow the discount to NAV, but because the manager is on both sides, the committee's independence is key.
I've gathered the filings and the reporting on the deal. Here is the dossier.
Executive brief
A rumoured deal could take a listed lender private. On 6 October 2026, PitchBook reported that H.I.G.'s WhiteHorse Capital is seeking to move all assets of its listed business development company (BDC), WhiteHorse Finance (WHF), into a continuation vehicle (a new fund run by the same manager). That vehicle would hold about $680M of loans, bids were said to be "in the high 90s" (cents on the dollar) and the BDC would delist (PitchBook). The company has confirmed only a strategic review. The stock trades about 33% below its $11.82 net asset value (NAV) per share (Clark Street Value). That gap is why the reported bid range matters.
What changed and event timeline
Dividend reset
WHF cut its quarterly distribution from $0.385 to $0.25 per share. The board called it "difficult but necessary" to match payouts to earnings ().
Strategic review
The board formed a special committee of independent directors to look at "a sale or other corporate transaction." It set no deadline and promised no outcome (). The stock was at $6.95 ().
Continuation-vehicle report
Unnamed sources told PitchBook the $680M vehicle includes assets from the joint venture with the State Teachers Retirement System of Ohio (STRS). Jefferies is advising. WhiteHorse did not comment (;).
9–10 Nov 2026: Q3 results
NAV per share rose to $11.82. Core net investment income (NII) was $0.224 per share. The board declared a $0.17 special distribution, and management would not take questions on the review (;).
Commentary
A blogger who discloses owning WHF shares called the reported structure "a liquidation disguised as a continuation fund." The blogger estimates value at about $10.50 per share, against a $7.95 share price ().
Capabilities and access
- Vehicle: WhiteHorse Finance, Inc. (Nasdaq: WHF), a BDC managed by an affiliate of H.I.G. Capital.
- Portfolio at 30 Sep 2026: $569.1M fair value across 64 companies, about 70.7% first lien (SEC 8-K).
- STRS joint venture: $332.6M across 43 issuers, at 0.93x leverage (Investing.com).
Read the full section
- Vehicle: WhiteHorse Finance, Inc. (Nasdaq: WHF), a BDC managed by an affiliate of H.I.G. Capital.
- Portfolio at 30 Sep 2026: $569.1M fair value across 64 companies, about 70.7% first lien (SEC 8-K).
- STRS joint venture: $332.6M across 43 issuers, at 0.93x leverage (Investing.com).
- Reported structure: a closed-end continuation vehicle funded by private-credit secondaries investors (PitchBook).
- Not disclosed: buyer, price, timing, and whether WHF holders would get cash or units.
Technical analysis for researchers and developers
- Earnings shortfall: Q3 GAAP NII was $0.207 and core NII $0.224, both below the $0.25 dividend.
- Refinancing: $75M of 4.00% notes mature on 15 Dec 2026 (PR Newswire). On the call, management cited $85M of unsecured notes maturing in December (Investing.com).
- Reconciling the $680M: WHF's portfolio ($569M) includes its stake in the JV, so it cannot simply be added to the JV's $332.6M.
Read the full section
- Earnings shortfall: Q3 GAAP NII was $0.207 and core NII $0.224, both below the $0.25 dividend. Gross leverage was 1.29x and net 1.20x (SEC 8-K; Investing.com).
- Refinancing: $75M of 4.00% notes mature on 15 Dec 2026 (PR Newswire). On the call, management cited $85M of unsecured notes maturing in December (Investing.com). The blog estimates replacement debt at about 7.5%.
- Reconciling the $680M: WHF's portfolio ($569M) includes its stake in the JV, so it cannot simply be added to the JV's $332.6M. How PitchBook's $680M figure is built is not public.
Claims and evidence
- Continuation vehicle, $680M size, high-90s bids, Jefferies as adviser: PitchBook, citing unnamed sources (PitchBook). The company has not confirmed it.
- Strategic review: confirmed in an SEC filing (8-K).
- About $10.50 per share value and about 30% upside: the blogger's own estimate, written by a shareholder (Clark Street Value).
Read the full section
- Continuation vehicle, $680M size, high-90s bids, Jefferies as adviser: PitchBook, citing unnamed sources (PitchBook). The company has not confirmed it. A secondaries newsletter repeats the report but adds no new sourcing (The Secondary Brief).
- Strategic review: confirmed in an SEC filing (8-K).
- About $10.50 per share value and about 30% upside: the blogger's own estimate, written by a shareholder (Clark Street Value).
- No other independent reporting confirms the deal.
Context and prior work
- Closest precedent: BlackRock TCP Capital (TCPC) sold 95% of a vehicle holding about $523M of loans to Pantheon on 4 Aug 2026. TCPC expected the sale to cut NAV by about 10.4% (TCPC release; Alternative Credit Investor).
- Market activity: in the same week as the PitchBook report, Blackstone raised about $1B for a credit continuation vehicle, and Partners Group launched an evergreen fund that buys credit secondaries (The Secondary Brief).
Read the full section
- Closest precedent: BlackRock TCP Capital (TCPC) sold 95% of a vehicle holding about $523M of loans to Pantheon on 4 Aug 2026. TCPC expected the sale to cut NAV by about 10.4% (TCPC release; Alternative Credit Investor).
- Market activity: in the same week as the PitchBook report, Blackstone raised about $1B for a credit continuation vehicle, and Partners Group launched an evergreen fund that buys credit secondaries (The Secondary Brief).
Limitations, safety and contested findings
- Debt maturing in December: the 2021 prospectus says $75M, and management cited $85M on the call.
- Selling all assets vs. part of them: TCPC sold part of its book and kept running.
- Asset quality: non-accruals fell to 2.0% of the debt portfolio at fair value, from 3.6% (Investing.com).
Read the full section
- Debt maturing in December: the 2021 prospectus says $75M, and management cited $85M on the call.
- Selling all assets vs. part of them: TCPC sold part of its book and kept running. The reported WHF deal would move all assets and delist the BDC.
- Asset quality: non-accruals fell to 2.0% of the debt portfolio at fair value, from 3.6% (Investing.com). The blog says about 25% of loans date from before 2022 and some positions were restructured.
- Uncertain outcome: the company says the review may not lead to any transaction (8-K).
Business and practitioner implications
- A possible exit for small BDCs: a BDC trading well below NAV could pass its loans to a manager-run fund rather than sell them one by one.
- Conflict of interest: the manager would sit on both sides of the deal, which makes the special committee's independence important.
- Signal for other BDCs: if the deal happens, its final price would be a public test of private-credit marks at a small BDC.
Read the full section
- A possible exit for small BDCs: a BDC trading well below NAV could pass its loans to a manager-run fund rather than sell them one by one. Direct-lending loans usually need the borrower's consent to trade, so keeping the same manager avoids that hurdle (Clark Street Value).
- Conflict of interest: the manager would sit on both sides of the deal, which makes the special committee's independence important.
- Signal for other BDCs: if the deal happens, its final price would be a public test of private-credit marks at a small BDC.
The source trail.
Sources (12)
WhiteHorse Finance: BDC Pursuing Strategic Alts, Continuation Fund Rumor
Article text retrieved; extracted text may omit tables or interactive elements.
clarkstreetvalue.blogspot.com