
StocksEquities, earnings & valuations
Floor & Decor Cuts 2026 EBITDA Outlook and Slows 2027 Store Openings as Home Sales Hit 16-Year Low
Floor & Decor cut its fiscal 2026 EBITDA range and slowed 2027 store openings, even though third-quarter EPS rose 15%. In October, existing-home sales fell to their slowest pace since 2010, which weakens the housing turnover its outlook depends on.
From the MBI Deep Dives article of November 12, 2026 and cited sources: Third-quarter results held up, but the outlook did not. [3] [4] [5]
SOURCES[3] FND Q2 FY2026 release ir.flooranddecor.com[4] FND Q3 FY2026 release ir.flooranddecor.com[5] Yahoo Finance/StockStory: FND Q3 2026 finance.yahoo.com
 AT Pulse research deskPublished · Updated · 5 min read · AI-assisted analysis
AI-assisted, not human-edited. Methodology Corrections Who owns this site
- Original source
- MBI Deep Dives article, independent perspective
- Brief by
- AT Pulse research desk AI-assisted; publisher and contact on the desk page
- When
- November 12, 2026 article published
- Covered
- Nov 14 edition
- Evidence
- 9 sources across 8 sites
- 1Floor & Decor 3Q’26: Déjà Vu, But Priced For A Lost Decadembi-deepdives.com
- 2NAR: October 2026 existing-home salesnar.realtor
- 3FND Q2 FY2026 releaseir.flooranddecor.com
- 4FND Q3 FY2026 releaseir.flooranddecor.com
- 5Yahoo Finance/StockStory: FND Q3 2026finance.yahoo.com
- 6Mohawk Q3 2026 releaseir.mohawkind.com
Reach: not measured yet
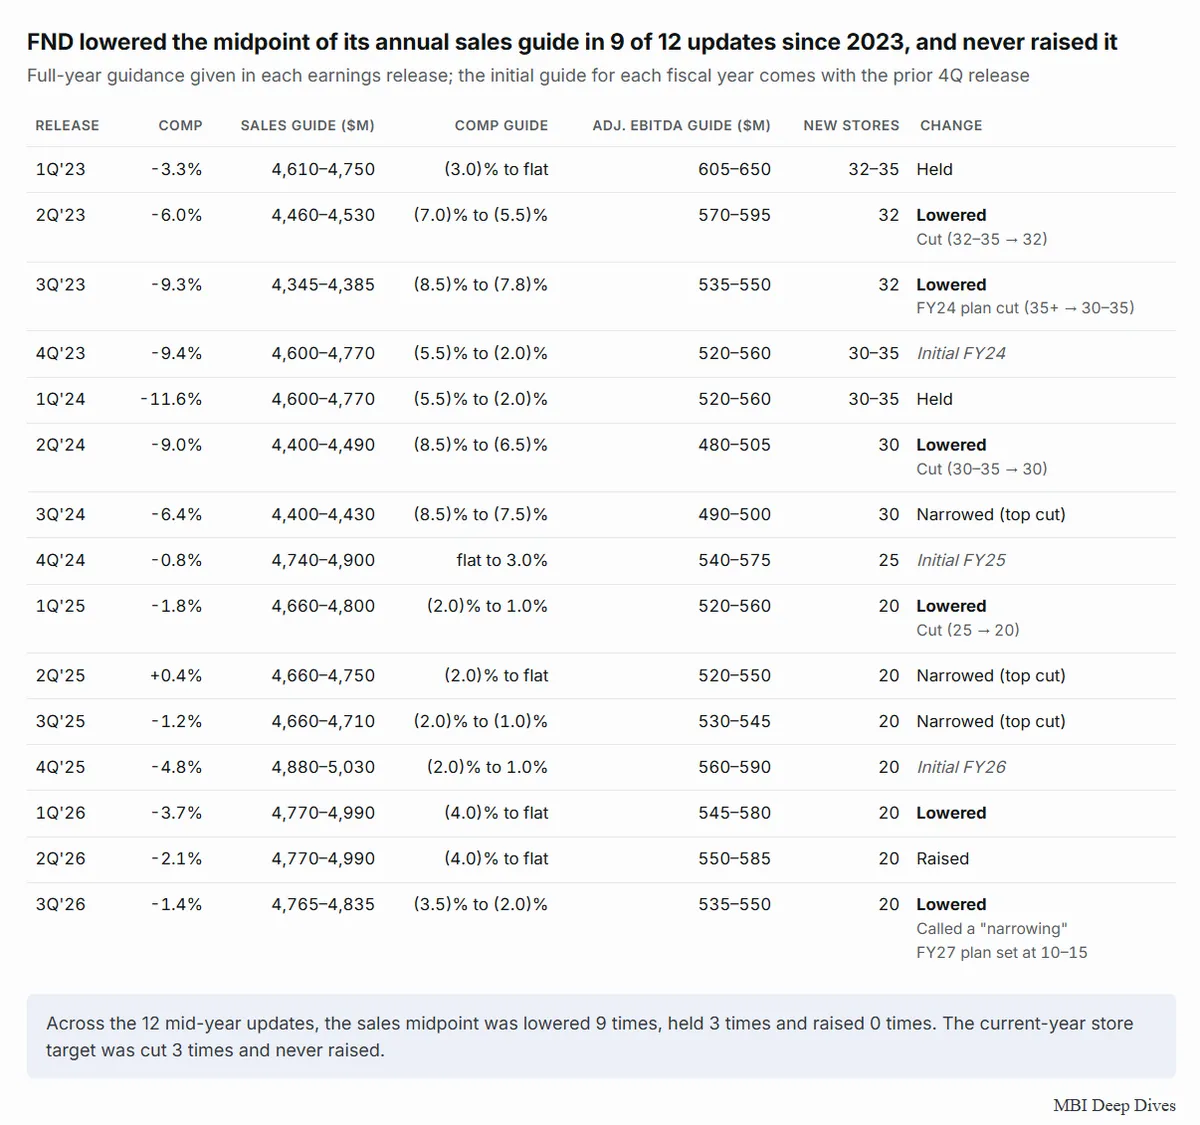
Third-quarter results held up, but the outlook did not. Net sales rose 3% to about $1.21 billion and diluted EPS climbed 15%, even though comparable sales fell 1.4%. Still, fiscal 2026 adjusted EBITDA guidance dropped to $535–550 million from $550–585 million in July, below consensus. The 2027 store opening plan fell to 10–15. [3] [4] [5]
This fits a pattern. By MBI Deep Dives' count of company releases, the full-year outlook has been cut or narrowed in nine of 12 mid-year updates since early 2023. In each of 2023–2025, results ended below February guidance but met the lowered October guidance. This is an analyst's tally, not an audited dataset. [1]
Industry data point to the same weakness. Mohawk said flooring demand softened as the third quarter ended, stayed weak through October and should fall further in 2027. NAR reported October existing-home sales at a 3.75 million annual rate, the lowest since 2010, with 30-year mortgage rates averaging about 7.3%. [2] [6] [7] [8]
Margins face several headwinds in 2027. Floor & Decor laps one-time tariff refunds, Mohawk expects cost inflation to keep pushing supplier prices up, and a new Pro loyalty program launches nationally. Pro customers are the bright spot: they now make up about 55% of retail sales, and September Pro sales grew 9%. [1] [7] [9]
On the evidence, Floor & Decor's results track existing-home turnover, which is at a 16-year low, and its main supplier expects lower 2027 volumes. The likely implication, not yet proven, is that early 2027 guidance could again prove too optimistic.
Executive brief
Floor & Decor (FND) has now cut or narrowed its full-year outlook in nine of the 12 mid-year updates since 1Q'23, according to MBI Deep Dives' review of company releases. On October 29, 2026, it lowered its fiscal 2026 adjusted EBITDA range to $535–550 million, entirely below the July range of $550–585 million. It also slowed 2027 store openings to 10–15, down from its usual 20. Two weeks later, NAR reported October existing-home sales at a 3.75 million annual rate, the lowest since August 2010. That is the demand driver FND's guidance depends on. The quarter itself held up: EPS rose 15% even though comparable-store sales fell.
What changed and event timeline
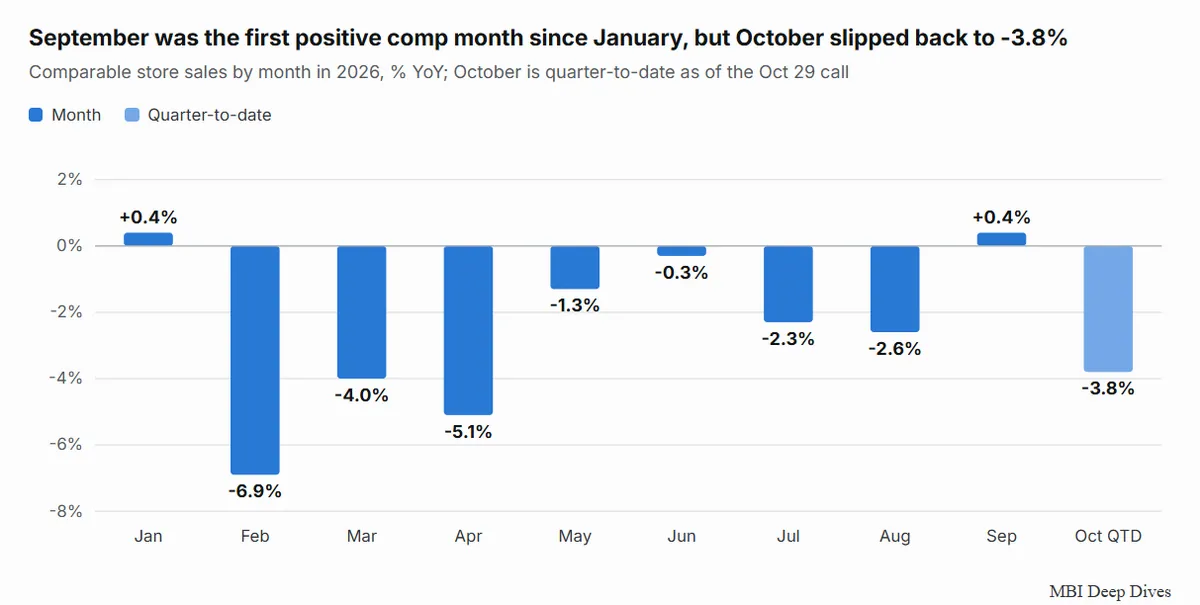
Outlook widened, top end kept at flat comps
FND guided fiscal 2026 comparable sales of −4.0% to flat, adjusted EBITDA of $550–585 million and 20 new stores. It said comps improved from −5.1% in April to near flat in June.
Q3 EPS up, guidance down
Net sales rose 3.0% to $1.21 billion, comps fell 1.4% and diluted EPS rose 15% to $0.61. FY26 comp guidance moved to −3.5% to −2.0%.
More detail
Shares fall after the print
The stock dropped 4.7% right after the release. The EBITDA guidance midpoint of $542.5 million was below the $556.2 million consensus.
Mohawk reports the same weak October
The largest flooring maker said demand weakened as Q3 ended and stayed soft through October, with the builder channel hit hardest. It expects market volumes to fall in 2027.
More detail
Existing-home sales hit a 16-year low
Sales fell 5.5% from September and 8.8% from a year earlier. Freddie Mac's 30-year mortgage rate averaged 7.33% in October.
Capabilities and access
Read the full section
New fiscal 2026 guidance (a 53-week year) compared with July, per FND Q3 and FND Q2:
- Net sales: $4.765–4.835 billion, previously $4.77–4.99 billion.
- Diluted EPS: $2.19–2.29, previously $2.20–2.45.
- Adjusted diluted EPS: $1.88–1.98, previously $1.88–2.13.
- Footprint: 282 warehouse stores plus five design studios. The 2026 plan is still 20 openings.
Technical analysis for researchers and developers
- How guidance has tracked actual results: MBI found that in 2023, 2024 and 2025, sales, comps and adjusted EBITDA all finished below the low end of February guidance.
- Gross margin mechanics: About $14 million of IEEPA tariff refunds flowed through Q3, with about $8 million left for Q4. MBI estimates gross margin excluding refunds fell about 90 basis points.
Read the full section
- How guidance has tracked actual results: MBI found that in 2023, 2024 and 2025, sales, comps and adjusted EBITDA all finished below the low end of February guidance. Each year they still met or beat the lowered October guidance (MBI). This is the author's tally of company releases, not an audited dataset.
- Gross margin mechanics: About $14 million of IEEPA tariff refunds flowed through Q3, with about $8 million left for Q4. Diesel and supply-chain costs cut gross margin by roughly 100 basis points in Q3, and management expects 120–140 basis points of pressure in Q4 (TradingKey transcript summary). MBI estimates gross margin excluding refunds fell about 90 basis points.
Claims and evidence
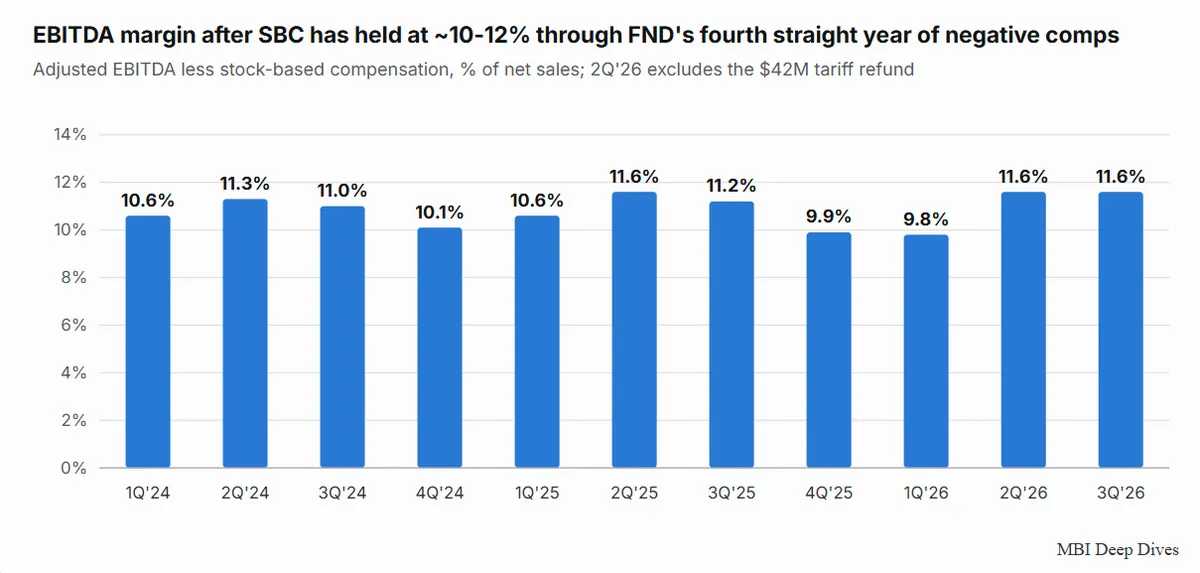
- Monthly comps: July −2.3%, August −2.6%, September +0.4% (the first positive month since January), October quarter-to-date about −3.8% (TradingKey).
- Pro customers: Pros were about 55% of retail sales, up from about 50%, and September Pro sales grew 9% (TradingKey).
- Store economics: Mature stores average about $20 million in sales, down from about $22 million, at roughly 23% four-wall EBITDA margins.
Read the full section
- Monthly comps: July −2.3%, August −2.6%, September +0.4% (the first positive month since January), October quarter-to-date about −3.8% (TradingKey). Management linked October to mortgage rates above 7%.
- Pro customers: Pros were about 55% of retail sales, up from about 50%, and September Pro sales grew 9% (TradingKey).
- Store economics: Mature stores average about $20 million in sales, down from about $22 million, at roughly 23% four-wall EBITDA margins. This figure appears only in MBI's account of the call.
- Consensus: The EPS guidance midpoint was 2.6% above consensus while EBITDA guidance was below it (Yahoo/StockStory).
Context and prior work
Mohawk offset $117 million of cost inflation with $85 million of pricing and $47 million of productivity gains. MBI reads this as supplier price pressure on FND's 2027 gross margin. Housing inventory reached 5.1 months of supply, the highest since November 2015 (NAR).
Read the full section
Mohawk offset $117 million of cost inflation with $85 million of pricing and $47 million of productivity gains. It expects mid-single-digit cost inflation to continue into early 2027 (Mohawk transcript). MBI reads this as supplier price pressure on FND's 2027 gross margin. MBI also cites a Home Depot CFO remark from August that housing turnover is at a record low relative to the housing stock; that quote was not independently confirmed. Housing inventory reached 5.1 months of supply, the highest since November 2015 (NAR).
Limitations, safety and contested findings
- Where the reports differ: MBI estimates about 90 basis points of underlying gross-margin decline, while the transcript summary attributes about 100 basis points to diesel alone.
- Paywalled analysis: The headline "lost decade" valuation argument sits behind MBI's paywall and is not assessed here.
- Single-source items: Store-productivity and laminate/vinyl figures (laminate/vinyl down 3.0% in Q3.
Read the full section
- Where the reports differ: MBI estimates about 90 basis points of underlying gross-margin decline, while the transcript summary attributes about 100 basis points to diesel alone.
- Paywalled analysis: The headline "lost decade" valuation argument sits behind MBI's paywall and is not assessed here.
- Single-source items: Store-productivity and laminate/vinyl figures (laminate/vinyl down 3.0% in Q3; MBI also says its share of sales fell from ~28% to 23% since 2022) come only from MBI's account of the call.
- Store target: Management calls the 2027 slowdown temporary "pacing" and keeps its long-term goal of 500 U.S. stores (TradingKey).
Business and practitioner implications
- Reading the guidance: FND's annual outlook works mostly as a bet on existing-home turnover.
- Unit growth: 10–15 openings in 2027 means about 3–5% unit growth, versus about 7% in each of the last two years, per MBI.
- Margin headwinds for 2027: FND laps the tariff refunds, faces supplier price increases and adds a Pro loyalty program set for national launch in 1Q'27.
Read the full section
- Reading the guidance: FND's annual outlook works mostly as a bet on existing-home turnover. MBI argues February guidance should be discounted until it states a housing assumption.
- Unit growth: 10–15 openings in 2027 means about 3–5% unit growth, versus about 7% in each of the last two years, per MBI.
- Margin headwinds for 2027: FND laps the tariff refunds, faces supplier price increases and adds a Pro loyalty program set for national launch in 1Q'27. Pro mix is the main bright spot.
The source trail.
Sources (9)
Floor & Decor 3Q’26: Déjà Vu, But Priced For A Lost Decade
Article text retrieved; extracted text may omit tables or interactive elements.
mbi-deepdives.com